Brite Pass
Pay Faster
Next Time
Enable consumers to Pay by Bank in one step without selecting their bank again. One saved account, fewer clicks, higher retention.
What it Brite Pass?
Brite Pass is Brite Payments’ embedded returning-user identification feature designed to streamline Pay by Bank (A2A) checkouts. By recognising users across different merchants, it bypasses repetitive bank selection steps and cuts payment initiation times in half.*
Brite Pass
First Checkout
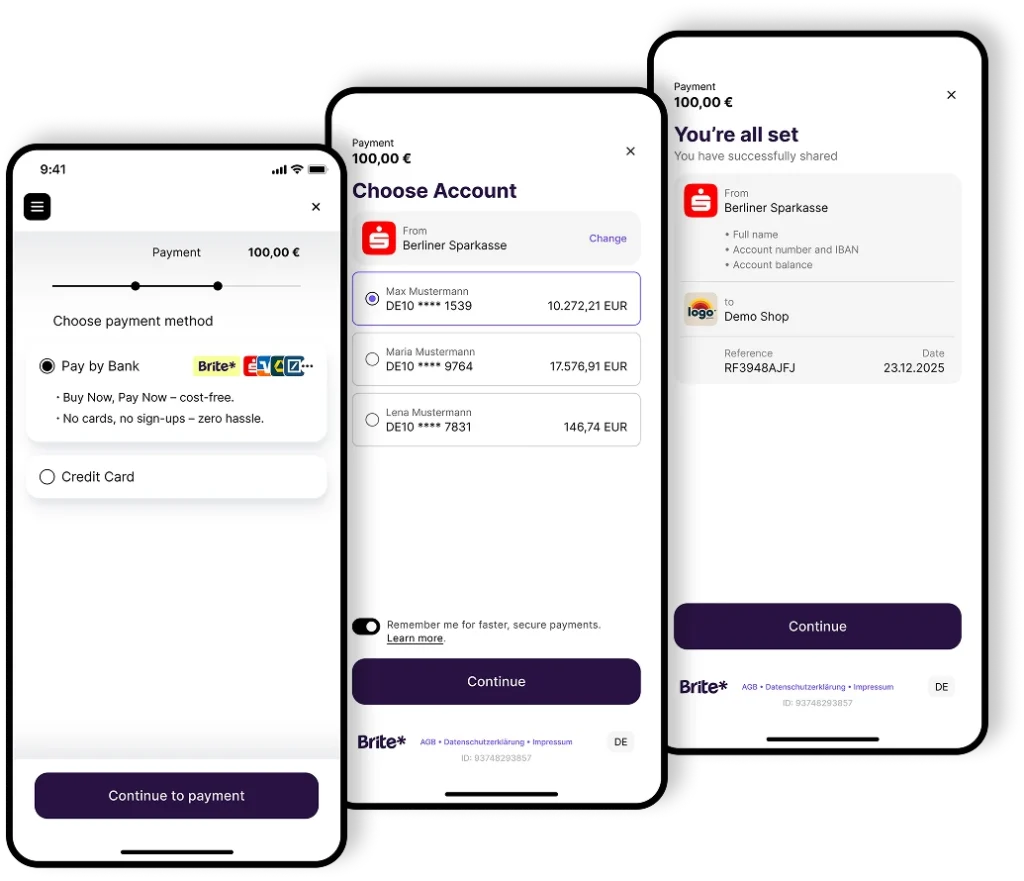
The consumer completes a standard Pay by Bank checkout and clicks the option to be remembered with a simple opt-in.
Smart Recognition
Brite Pass securely maps the consumer using API data (customer_id, email) or tamper-proof device identifiers.
Instant Return
On their next visit – at your checkout or any other Brite-enabled merchant – the consumer’s preferred bank account is pre-selected.
Coming soon… One-Touch Payment
Consumers initiate payments in just one step using Face ID, Fingerprint biometrics, or secure passkeys – meaning enhanced, secure, seamless payments across all Brite merchants and devices that support passkeys.
Fast-Track
Returning Sales
Turn first-time users into repeat buyers with a frictionless account-to-account payment journey.
Cut Checkout Time by 50%*
Remove manual IBAN typing, bank selection, and account eligibility checks to route consumers straight to payment authorisation.
Network-Wide Recognition
Immediate identification at checkout for any consumer who saves their account at a participating Brite merchant.
Enhanced Security and Stability
Identification across merchants and any device using whichever favoured biometric authentication (coming soon).
Maximum Retention
Deliver an effortless checkout experience that consumers expect. Fewer clicks mean fewer abandoned carts.
Why add Brite Pass to your checkout?
“By replacing multi-step bank redirections with pre-selected account recognition, Brite Pass removes the primary drivers of cart abandonment in Pay by Bank flows.”
Built for Seamless Conversion
Central Consumer ID
Anchor identity at the consumer level, for cross-merchant recognition across all customers of Brite.
Contract-Based Compliance
Operates under a clear performance-of-contract legal framework with built-in, one-click user opt-out control.
Direct PIS Execution
Eliminates background AIS checks, triggering instant payment execution directly with saved account metadata.
Brite Performance
Tap into a cross-merchant network that reduces payment friction.
50%
Faster payment completion time for returning consumers.
>90%
Recognition rate for returning user sessions via API and device matching.
Zero
No sensitive data stored: bank-grade compliance with no password/login caching.
Plug in and Cut Down the Friction
Brite Pass is built directly into the core Brite checkout interface. No extra APIs, third-party middleware, or complex SDK maintenance required.
Your Brite Pass Questions Answered
Any more questions?
Does a Brite Pass user need an account or app?
No. There are no app downloads, passwords, or separate account registrations required for a consumer to use Brite Pass.
Are banking credentials stored when using Brite Pass?
Brite never stores credentials; we are in alignment with the EU-wide PSD2 regulation, and we use bank account identifiers, such as the IBAN, needed to initiate payments, never passwords or login credentials.
How are returning consumers recognised by Brite Pass?
Consumers are identified seamlessly via secure merchant API attributes (like email or customer ID) or tamper-proof local browser tokens.
How does cross-merchant recognition work in Brite Pass?
Because identity is tied to a central consumer profile (BriteCID, a unique Brite Customer ID), a consumer who opts in on site A is automatically recognised when paying on site B.
Can a consumer opt out or remove saved accounts?
Yes, Users of Brite can uncheck the option to be remembered directly inside the checkout UI at any time.
Does Brite Pass require a complex API integration?
No. Brite Pass comes included natively within the standard Brite payment widget – no additional development work is required.
How does Brite Pass handle long-term AIS consents?
It eliminates them completely by moving to a momentary AIS / direct PIS model, removing the hassle of consent renewals for payments.
Which markets and industries does Brite Pass work across?
Brite Pass is set to be available across all of Brite’s core European markets and supports all verticals, including e-commerce, regulated gaming, financial services, and travel. It will first be offered in Germany and Finland, then roll out to all other markets.
Any more questions?