End the Waiting Game
with Pay by Bank
End the Waiting Game with Pay by Bank
Our Products
Instant Payments
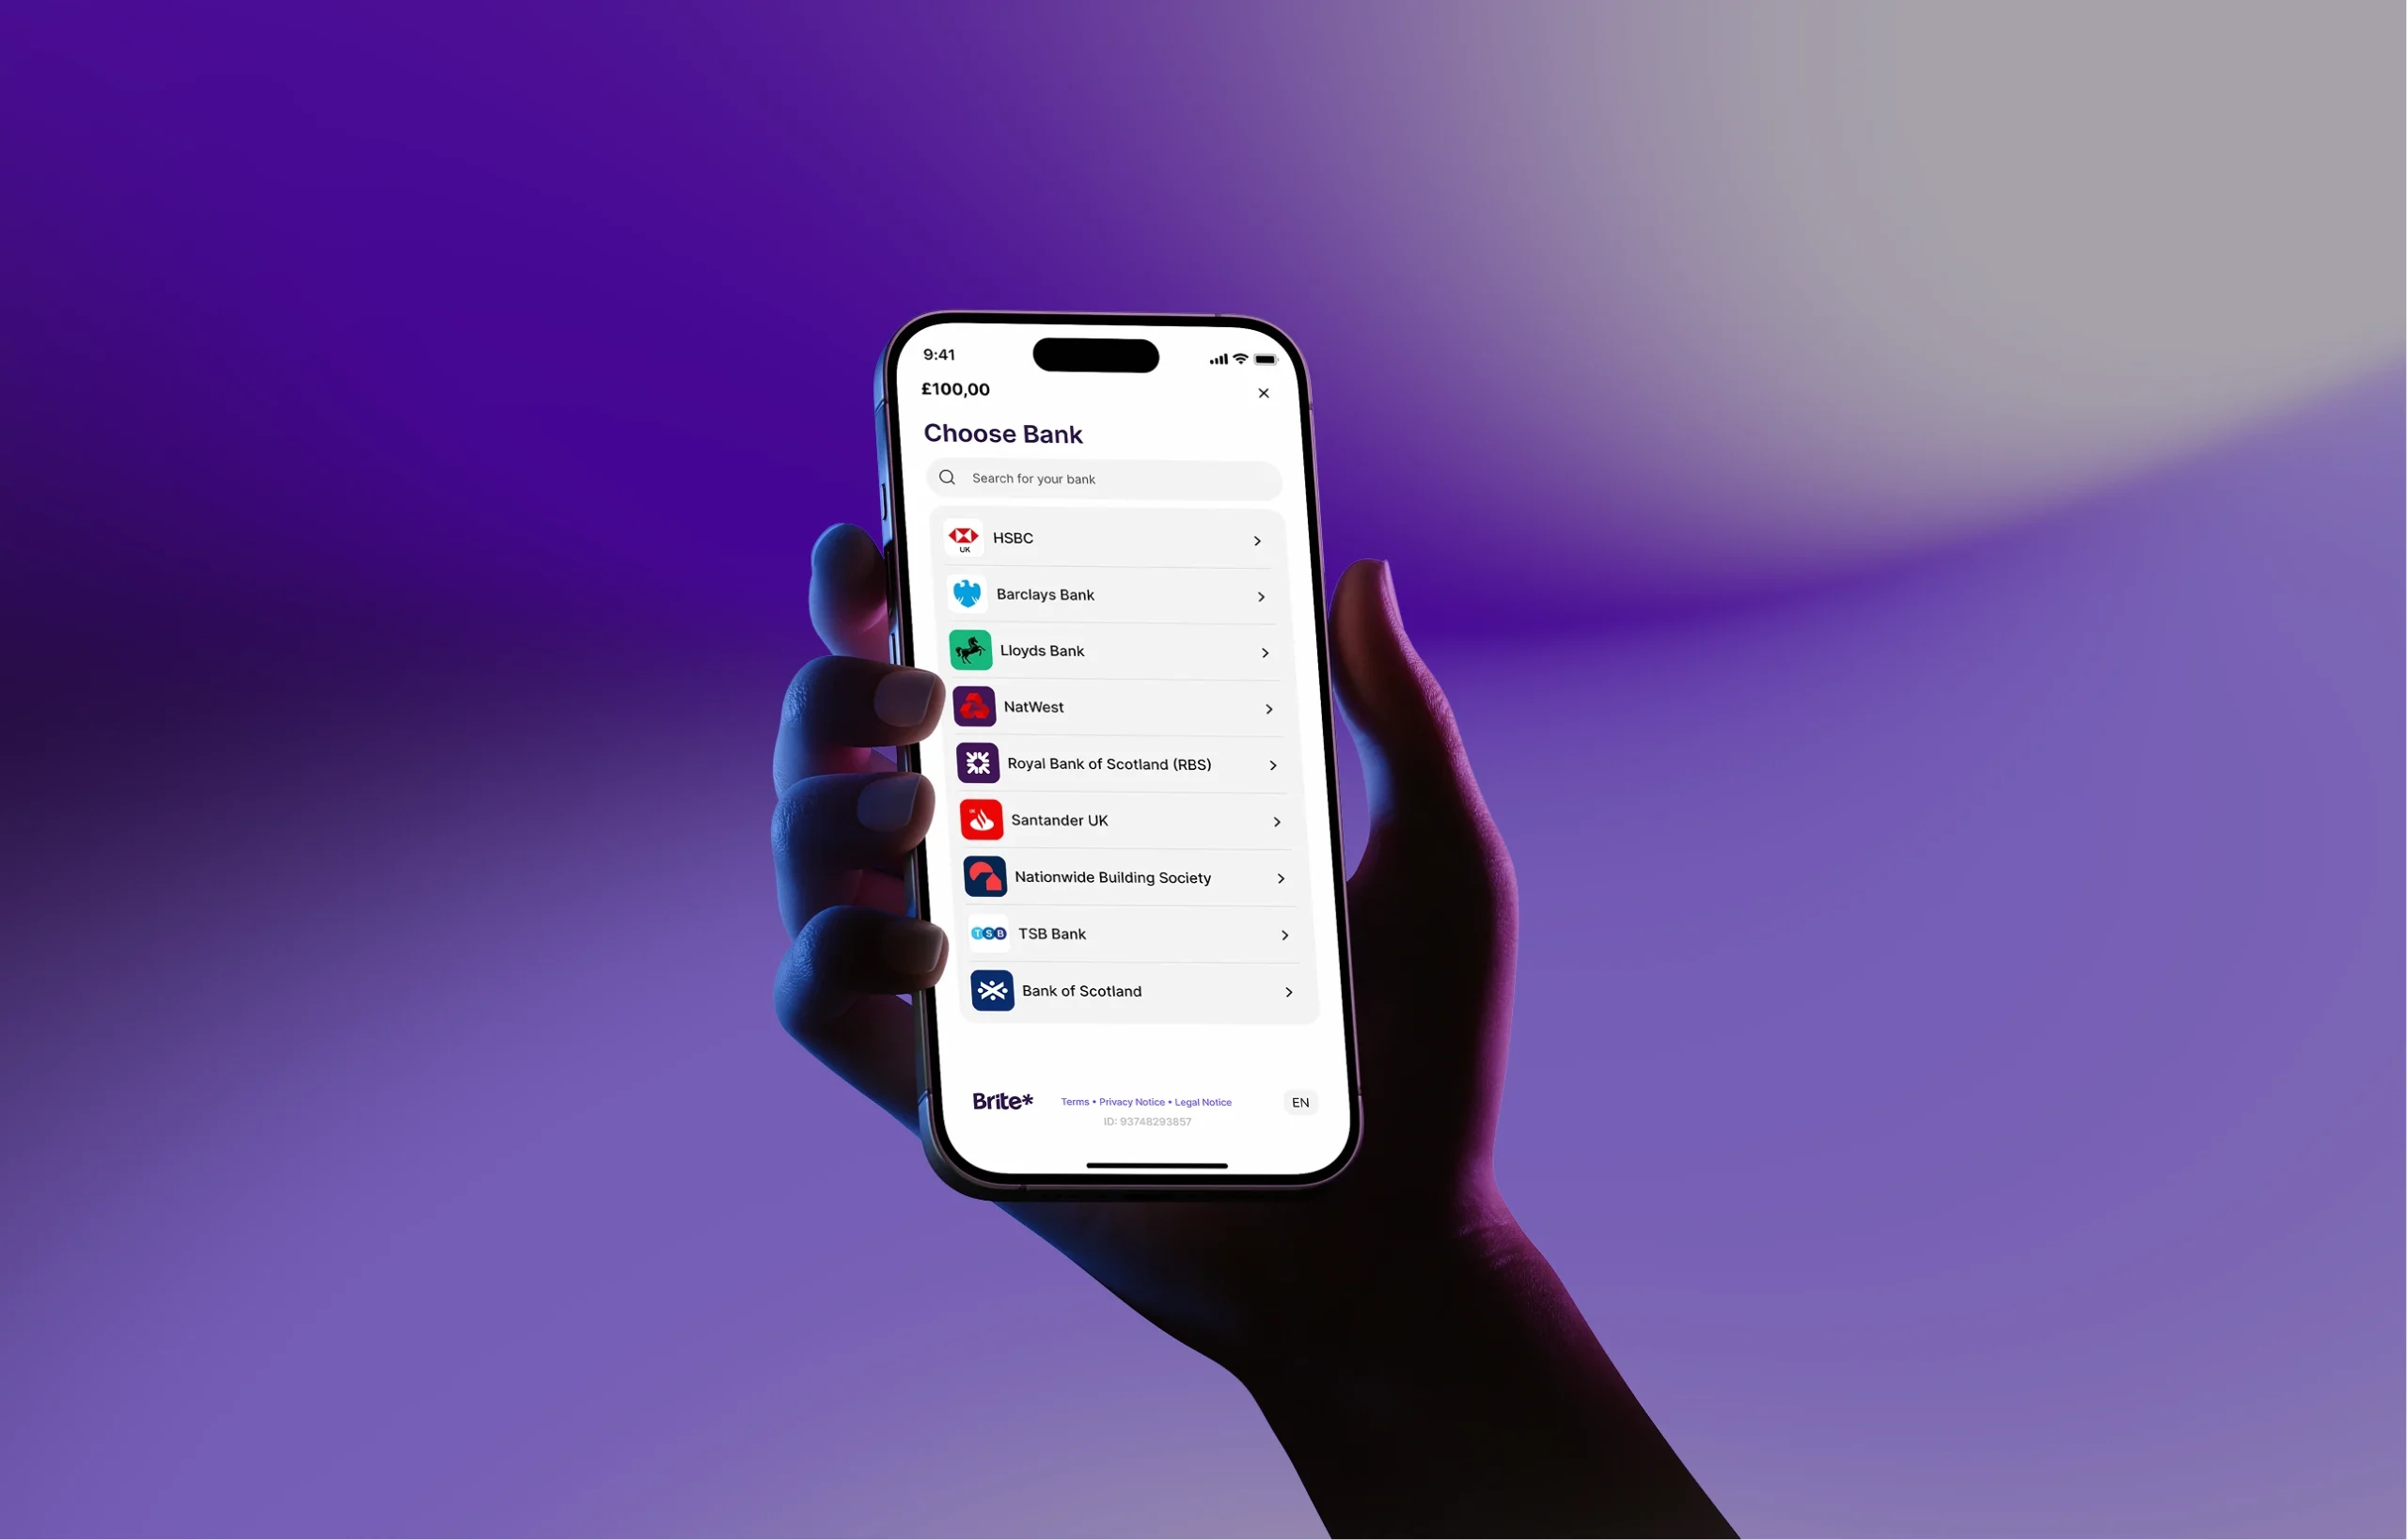
Fast and Secure Pay by Bank
Instant Payouts
Accurate and Instant Payouts
Speed. Reliability. Support. Solved.
Fast In. Fast Out.
UX Refined
Real Support
Rock Solid
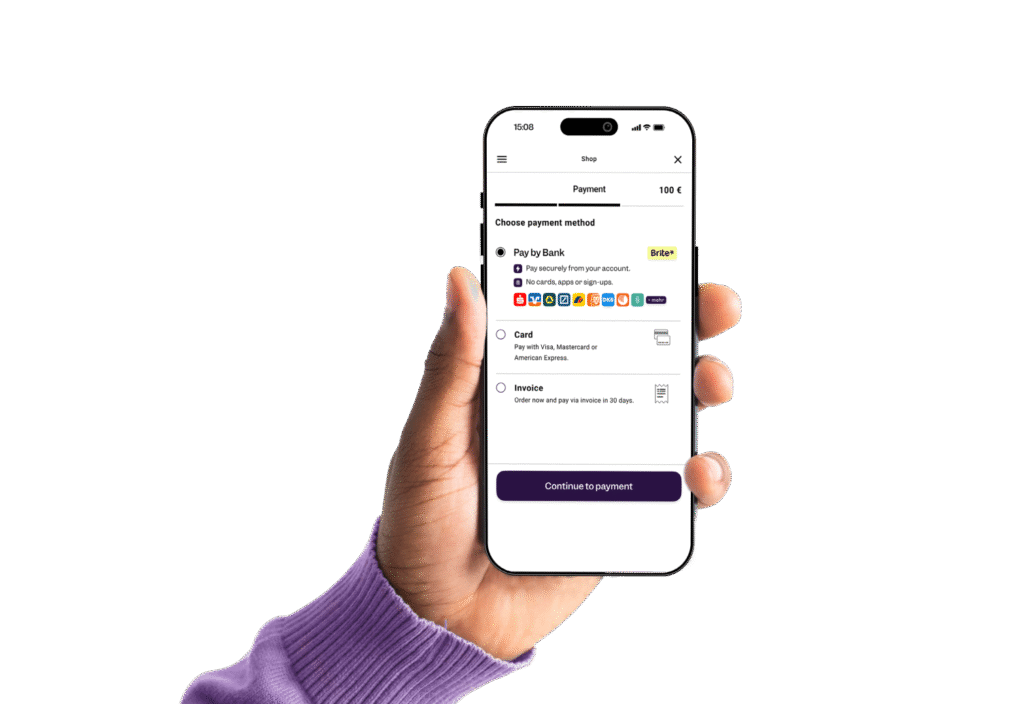
A Pay by Bank flow that converts
Simple steps for Payout control
Brite Group Customers
E-commerce
Financial Services
Gaming
Fast-Track Your Go-Live
Security isn’t a feature – it’s our foundation
Trusted stability
Brite uses HTTPS encryption to protect information transferred through its systems and website, applies two-factor authentication and access controls, and conducts penetration testing with external support.
Fraud resilience
With direct bank authentication and Strong Customer Authentication (SCA) at the core of Open Banking, Brite goes one step further. Using our infrastructure, we keep fraud and unsettled payment rates impressively close to zero.
Compliance excellence
Brite Payments Limited is an FCA-authorised Electronic Money Institution (EMI), supported by a comprehensive compliance and risk-management framework. Our controls are risk-based, subject to continuous monitoring, and mapped to applicable requirements, including AML and financial crime regulation, the Payment Services Regulations, UK GDPR, operational resilience requirements, and accessibility standards.
Latest Resources
Your Brite Payments Questions Answered
What is Brite Payments?
Brite Payments Limited is the UK-regulated provider of Brite’s UK e-money and payment services. It is part of the Brite Group. Its Swedish sister company, Brite AB, is a Swedish fintech and licensed Payment Institution supervised by Finansinspektionen.
Where is Brite Payments based?
Brite Payments Limited is headquartered in London, UK. While Brite Group is headquartered in Stockholm (Sweden), with additional offices in Malaga (Spain) and Valletta (Malta).
How secure is a Pay by Bank transaction for my customers and my business?
Pay by Bank transactions via Brite are exceptionally secure. They are built on the PSD2 Open Banking framework, which mandates Strong Customer Authentication (SCA)—a two-factor verification (such as biometrics) performed directly by the consumer’s own bank.
For your business, this means no sensitive card data is stored, drastically reducing your fraud risk and PCI compliance burden.
How does Brite help me save money and increase conversion?
We aim to improve your financial performance through two key value drivers:
Cost Savings: By bypassing card networks, we eliminate high interchange fees and chargeback costs.
Conversion: We remove friction (no card details, no registration) and optimize the checkout UX, with features like ‘Pay Faster Next Time’ enabling payments up to 40% faster than standard flows, leading to higher completed sales.
Which banks and countries does Brite Payments cover in the UK and Europe?Which banks and countries does Brite Payments cover in the UK and Europe?
Our Instant Payment Network (IPN) is connected to over 3,800 banks and operates in 27 markets across the UK and Europe, allowing merchants to easily make cross-border payments, payouts, and treasury transfers across the continent.
Markets where Brite products are available:
Austria
Belgium
Croatia
Cyprus
Denmark
Estonia
Finland
France
Germany
Greece
Hungary
Ireland
Italy
Latvia
Lithuania
Luxembourg
Malta
Netherlands
Norway
Portugal
Romania
Slovakia
Slovenia
Spain
Sweden
Switzerland
United Kingdom
How long does it take to integrate Brite into my website or platform?
Brite offers a clean, developer-friendly API designed for efficiency. While actual go-live time depends on your internal resources, our platform, including features like the Checkout UX Assistant (CHUX), is designed to help businesses integrate and launch their first solution in a matter of days or weeks.
What's the difference between open banking, account-to-account payments, and Pay by Bank?
Open Banking: The regulatory framework allowing banks to share financial data and services securely.
For consumers, open banking is a secure framework allowing them to initiate bank payments or share financial data (with their explicit consent) via authorised third-party providers (like fintech apps) through APIs, enabling new, innovative services like faster payments, budgeting, easier loan applications, and consolidated account views, fostering competition and giving consumers more control over their money. It opens up traditionally closed bank systems to trusted companies, with consumers holding the keys to their data.
Account-to-Account Payments (A2A): The technical term for the direct funds transfer between bank accounts, without the reliance on card networks.
A2A payments are direct transfers of money from one bank account to another, without intermediaries such as card networks (Visa, Mastercard) or payment processors, making them faster, cheaper, and more secure for peer-to-peer (P2P) payments, bill payments, e-commerce, and business transactions. Using bank-specific rails, A2A moves funds directly from a payer’s balance to a payee’s, reducing fraud risks and processing fees.
Pay by Bank: The common, consumer-facing term for A2A payments initiated via open banking technology.
Pay by Bank means making an online payment directly from your bank account using your online banking login, facilitated by secure technology like Open Banking for quick, card-free, and often cheaper transactions, where you simply log in and approve the payment in your bank’s app or website. It’s a modern alternative to card payments, moving funds instantly (or near-instantly) from your account to the merchant’s.
How is Brite Payments different from a credit/debit card processor?
Brite differs fundamentally from a credit/debit card processor by:
Cost: Offering significantly lower transaction costs by eliminating expensive card network interchange fees.
Risk: Providing zero chargeback liability, as bank-verified payments are far more secure.